DIRECT TAXES MANUAL by Bharat Law House is a Practice book on Income Tax on Conferenza, priced at ₹7,825 (10% off MRP ₹8,695). Published by Bharat Law House. Order online with fast delivery across India.
- Price
- ₹7,825 · 10% off
- Course
- Practice
- Subject
- Income Tax
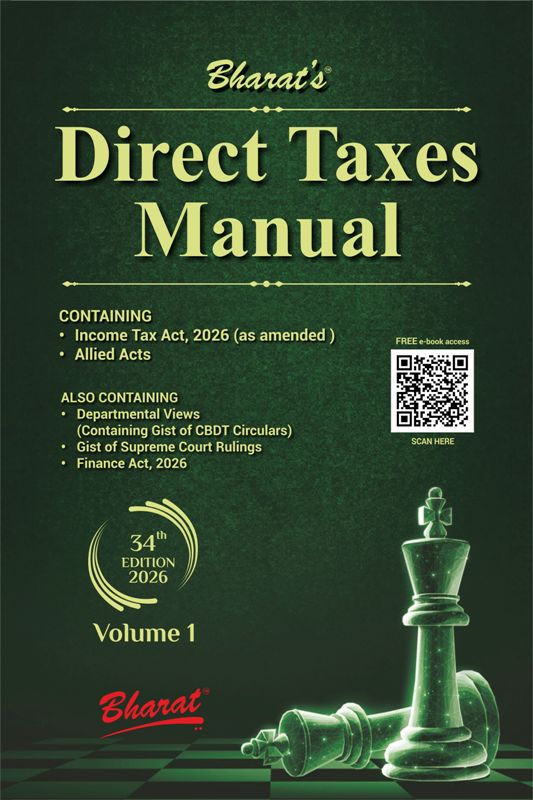
DIRECT TAXES MANUAL
Bharat Law House
About this book
Edition: 34th edn., 2026 (set of 3 Volumes)
ISBN: 978-93-4777-911-4
Pages: 5230
Author: Bharat Law House
1. THE INCOME-TAX ACT, 2025(As amended by the Finance Act, 2026)Statement of Objects and Reasons CHAPTER IPRELIMINARYSection No. 1. Short title, extent and commencement 2. Definitions 3. Definition of “tax year” CHAPTER IIBASIS OF CHARGE4. Charge of income-tax 5. Scope of total income 6. Residence in India 7. Income deemed to be received and dividend deemed to be income in a tax year 8. Income on receipt of capital asset or stock-in-trade by specified person from specified entity 9. Income deemed to accrue or arise in India 10. Apportionment of income between spouses governed by Portuguese Civil Code CHAPTER IIIINCOMES WHICH DO NOT FORM PART OF TOTAL INCOMEA.—Incomes not to be included in total income11. Incomes not included in total income B.—Incomes not to be included in total income of political parties and electoral tr12. Incomes not included in total income of political parties and electoral trusts CHAPTER IVCOMPUTATION OF TOTAL INCOMEA.—Heads of income13. Heads of income 14. Income not forming part of total income and expenditure in relation to such income B.—Salaries15. Salaries 16. Income from salary 17. Perquisite 18. Profits in lieu of salary 19. Deductions from salaries C.—Income from house propertySection No. 20. Income from house property 21. Determination of annual value 22. Deductions from income from house property 23. Arrears of rent and unrealised rent received subsequently 24. Property owned by co-owners 25. Interpretation D.—Profits and gains of business or profession26. Income under head “Profits and gains of business or profession” 27. Manner of computing profits and gains of business or profession 28. Rent, rates, taxes, repairs and insurance 29. Deductions related to employee welfare 30. Deduction on certain premium 31. Deduction for bad debt and provision for bad and doubtful debt 32. Other deductions 33. Deduction for depreciation 34. General conditions for allowable deductions 35. Amounts not deductible in certain circumstances 36. Expenses or payments not deductible in certain circumstances 37. Certain deductions allowed on actual payment basis only 38. Certain sums deemed as profits and gains of business or profession 39. Computation of actual cost 40. Special provision for computation of cost of acquisition of certain assets 41. Written down value of depreciable asset 42. Capitalising impact of foreign exchange fluctuation 43. Taxation of foreign exchange fluctuation 44. Amortisation of certain preliminary expenses 45. Expenditure on scientific research 46. Capital expenditure of specified business 47. Expenditure on agricultural extension project and skill development project 48. Tea development account, coffee development account and rubber development account 49. Site Restoration Fund 50. Special provision in case of trade, profession or similar association 51. Amortisation of expenditure for prospecting certain minerals 52. Amortisation of expenditure for telecommunications services, amalgamation, demerger, scheme of voluntary retirement, etc. 53. Full value of consideration for transfer of assets other than capital assets in certain cases 54. Business of prospecting for mineral oils 55. Insurance business 56. Special provision in case of interest income of specified financial institutions 57. Revenue recognition for construction and service contracts 58. Special provision for computing profits and gains of business or profession on presumptive basis in case of certain residents 59. Computation of royalty and fee for technical services in hands of non-residents 60. Deduction of head office expenditure in case of non-residents Section No. 61. Special provision for computation of income on presumptive basis in respect of certain business activities of certain non-residents. 62. Maintenance of books of account 63. Tax audit 64. Special provision for computing deductions in case of business reorganisation of co-operative banks 65. Interpretation for purposes of section 64 66 Interpretation E.—Capital gains67. Capital gains 68. Capital gains on distribution of assets by companies in liquidation 69. Capital gains on purchase by company of its own shares or other specified securities 70. Transactions not regarded as transfer 71. Withdrawal of exemption in certain cases 72. Mode of computation of capital gains 73. Cost with reference to certain modes of acquisition 74. Special provision for computation of capital gains in case of depreciable assets 75. Special provision for cost of acquisition in case of depreciable asset 76. Special provision for computation of capital gains in case of Market Linked Debenture 77. Special provision for computation of capital gains in case of slump sale 78. Special provision for full value of consideration in certain cases 79. Special provision for full value of consideration for transfer of share other than quoted share 80. Fair market value deemed to be full value of consideration in certain case 81. Advance money received 82. Profit on sale of property used for residence 83. Capital gains on transfer of land used for agricultural purposes not to be charged in certain cases 84. Capital gains on compulsory acquisition of lands and buildings not to be charged in certain cases 85. Capital gains not to be charged on investment in certain bonds 86. Capital gains on transfer of certain capital assets not to be charged in case of investment in residential house 87. Exemption of capital gains on transfer of assets in cases of shifting of industrial undertaking from urban area 88. Exemption of capital gains on transfer of assets in cases of shifting of industrial undertaking from urban area to any Special Economic Zone 89. Extension of time for acquiring new asset or depositing or investing amount of capital gains 90. Meaning of “adjusted”, “cost of improvement” and “cost of acquisition” 91. Reference to Valuation Officer F.—IncomFrequently asked questions
What is DIRECT TAXES MANUAL?+
Edition: 34th edn., 2026 (set of 3 Volumes) ISBN: 978-93-4777-911-4 Pages: 5230 Author: Bharat Law House 1. THE INCOME-TAX ACT, 2025(As amended by the Finance Act, 2026)Statement of Objects and Reasons CHAPTER IPRELIMINARYSection No. 1. Short title, extent and commencement 2. Def
Who is the author of DIRECT TAXES MANUAL?+
Bharat Law House (Bharat Law House).
How much does DIRECT TAXES MANUAL cost?+
DIRECT TAXES MANUAL is available for ₹7825 (MRP ₹8695) on Conferenza, with fast delivery.
Which exam is DIRECT TAXES MANUAL for?+
Practice — Income Tax.
Is DIRECT TAXES MANUAL good for self-study of Income Tax?+
DIRECT TAXES MANUAL is a Income Tax book for Practice, suitable for self-study and revision. Pair it with practice and past papers for complete exam preparation.
Which is the best book for Income Tax?+
There's no single "best" book for Income Tax — the right choice depends on the syllabus coverage you need, the author's approach, the edition and your budget. DIRECT TAXES MANUAL by Bharat Law House is one Practice option; compare it with other Income Tax books on Conferenza by edition, coverage and price to pick what suits your preparation.
Is DIRECT TAXES MANUAL available as a free PDF download?+
DIRECT TAXES MANUAL is a paid book on Conferenza, delivered fast across India. For free PDFs — study material, RTPs, MTPs and suggested answers — visit https://conferenza.in/downloads.